
I’ll never forget the sterile smell of that recovery room or the way my stomach dropped when my phone buzzed with a credit alert while I was still on a morphine drip. There I was, physically broken, and suddenly my financial future felt just as fractured. I’d spent years [mastering credit repair](https://creditclaritys.com/mastering-credit-repair-dispute-errors-and-fico-optimization) and obsessively [monitoring my credit for small changes](https://creditclaritys.com/how-to-monitor-your-credit-for-small-changes-that-matter), only to realize that a long hospital stay is the ultimate FICO-killer. I made the mistake of thinking my creditors would have a ‘heart’ if I just called them later. They didn’t. By the time I could walk again, my score had plummeted because of a few missed cycles. It was a mess, but it taught me a vital lesson about the ‘move’ most people miss. We’re going to talk about how to stop that bleeding before it starts so you can focus on healing your body, not your bank account.
When Your Health Tanks Your FICO Score Usually Follows
Living through an extended medical leave is exhausting enough without the looming shadow of debt collectors. Most folks don’t realize that even a single [medical bill that went to collections unfairly](https://creditclaritys.com/how-to-handle-a-medical-bill-that-went-to-collections-unfairly) can stay on your record for years, dragging down your ability to get a loan or even a decent [cell phone plan](https://creditclaritys.com/why-your-score-matters-for-your-next-cell-phone-plan). I learned the hard way that silence is your worst enemy. I once ignored a bill for three weeks while in rehab, thinking it wasn’t a big deal. That ‘small’ mistake led to a cascade of [fico dispute errors](https://creditclaritys.com/understanding-fico-dispute-errors-and-credit-repair-hacks) that took me six months to untangle. Here’s a staggering reality: a study by the Consumer Financial Protection Bureau revealed that medical debt is the most common collection item on credit reports, affecting roughly 1 in 5 Americans.
Is This Move Actually Worth the Effort While I’m Recovering?
You might be thinking, ‘I can barely get out of bed, how am I supposed to manage a credit strategy?’ I get it. It feels like just more bureaucracy when you’re already at your limit. But the move I’m advocating for—proactive temporary hardship protection—takes less than twenty minutes and saves you years of [rebuilding credit after a crisis](https://creditclaritys.com/how-to-build-credit-fast-expert-tips-for-correcting-credit-errors-and-boosting-fico). It’s about setting up a perimeter. Have you ever felt like you had to choose between your health and your credit standing? It’s a choice no one should have to make. By the end of this, you’ll know exactly how to [verify a debt](https://creditclaritys.com/how-to-verify-a-debt-that-is-more-than-seven-years-old) and use the ‘hardship flag’ to your advantage so your score stays frozen in time while you get better.
Stop the Bleeding Before Your Score Crashes
Think of your credit report like a garden. If you stop watering it (making payments) for a few months while you’re in the hospital, the weeds (late payments) will take over. The move is to put your garden in ‘stasis.’ Most major lenders have unadvertised hardship programs designed for exactly this situation. They won’t offer it unless you ask, but getting that ‘hardship flag’ on your account acts like a temporary shield. It tells the FICO algorithm to pause the clock. I remember sitting in the hospital lobby, leaning against my IV pole, and calling my primary card issuer. I felt embarrassed, but that ten-minute call prevented a ’30-day late’ tag that would have haunted me for seven years. Using proven strategies to improve your credit dispute score starts with preventing the errors from happening in the first place.
Demand the Hardship Department Right Away
When you call, don’t just talk to the first person who answers. General customer service reps are trained to take payments, not to grant leniency. You need to ask for the ‘Hardship Department’ or ‘Loss Mitigation.’ These folks have the power to lower interest rates or defer payments without reporting you as ‘late’ to the bureaus. If you don’t do this, you’ll end up needing effective dispute error resolution later, which is much harder than a simple phone call. I once had an ER bill for $212 that I didn’t even know existed until it hit my report. Because I didn’t have a hardship flag, that tiny bill dropped my score by 80 points. It was a classic example of why monitoring your credit for small changes is a survival skill.
Keep a Log Like Your Life Depends on It
Every time you speak to a creditor or a medical billing office, write it down. Date, time, name of the rep, and exactly what they promised. This log is your ammunition if they break their word. This is the specific log you need to keep when calling bureaus or creditors. If they agree to a ‘pay-for-delete’ or a ‘deferment,’ you must get it in writing. Never trust a verbal promise from a collector. In fact, why you should never pay a collection before getting a written agreement is a rule you should live by. I once spent four months fighting a ‘late’ status because a rep told me I was ‘all set’ but never actually updated the system.
Address the Unfair Medical Bills Immediately
Medical billing is notoriously buggy. Coding errors are rampant. If you see a bill that looks wrong, don’t wait for it to go to collections. Use the No Surprises Act to your advantage and dispute the charge with the hospital’s billing advocate first. If it does slip through, you’ll need to know how to handle a medical bill that went to collections unfairly. Use the paperwork that proves a payment was made on time or that the insurance was supposed to cover it to force the bureau’s hand. This isn’t just about money; it’s about maintaining your FICO standing so that when you’re back on your feet, the world is still open to you.
Why Paying Off Collections Can Actually Freeze Your Progress
Most “gurus” tell you that the second you get out of the hospital, you should pay off every collection notice you find. I’m here to tell you that’s a rookie mistake that can backfire. In my experience, writing a check without a “pay-for-delete” agreement is like putting a band-aid on a broken leg—it looks like you did something, but the structural damage remains. In fact, why paying off a collection does not always raise your score is one of the most frustrating nuances of the FICO system. Older models, like the ones many mortgage lenders still use, don’t care if a collection is paid or unpaid; they just see that a collection existed. I once settled a $500 debt thinking I was a hero, only to watch my score sit perfectly still for three months. It’s a bitter pill to swallow when you’re already struggling.
Why did my score drop even further after I paid that old debt?
This is the “Oops” factor most people miss. When you pay an old, dormant collection, the collection agency updates the “Date of Last Activity.” To some older FICO algorithms, this looks like the debt is brand new again, potentially triggering a “re-aging” effect that drags your score down. You must know how to spot a re-aged debt on your credit report immediately before you engage with these agencies. According to research by FICO, the newer FICO 9 and 10 models actually ignore paid medical collections entirely, but the catch is that many lenders are still stuck on FICO 8. If your lender hasn’t upgraded, your payment won’t help you qualify for a better rate tomorrow.
Stop Using Templates Before the Bureau Robots Block You
Another trap is the “shotgun approach”—disputing every negative item at once using a template you found online. The bureaus use sophisticated OCR (Optical Character Recognition) to flag these. If they think a “credit repair mill” is working for you, they’ll label your request as frivolous. This is the problem with using credit repair software for complex errors. It’s far better to work on mastering credit repair dispute errors and fico optimization by sending personalized, hand-written letters that include the documentation that proves a payment was made on time. It takes longer, but it actually works. Have you ever fallen into this trap of thinking a quick-fix software would solve it all? Let me know in the comments. I’ve seen people lose years of progress because they tried to take the easy route with why you should avoid quick-fix credit repair schemes. Even when you are trying to build credit fast, the slow way is often the only way that sticks.
Spotting Zombie Debts Before They Re-Haunt Your Report
After a medical crisis, you might think you’ve cleared the field, only for a “zombie debt” to appear. This is debt that is past the statute of limitations but is sold to a new collector who tries to trick you into acknowledging it. If you make even a small payment, you might accidentally restart the clock on the legal statute. Before you talk to anyone, you must learn how to verify a debt that is more than seven years old. The nuance here is that “reporting time” (usually 7 years) and “suing time” (which varies by state) are different. Collectors count on you not knowing that. They might even try to report it as a new account, which is why fico insights how dispute errors affect your score and what to do are vital—you need to know the difference between a legitimate collection and a phantom one before you panic.
Once you’ve cleared the immediate wreckage of a hospital stay or a financial crisis, the real work begins—the boring, daily maintenance that separates the one-hit wonders from the long-term winners. I’ve seen people claw their way back from a 500 to a 720, only to let it slip because they stopped the very habits that got them there. You have to treat your credit profile like a living thing. For me, that meant moving away from the flashy apps and getting back to basics. I personally use a simple, manual Google Sheet to track my statement closing dates rather than just the payment due dates. Why? Because why your credit utilization ratio is more important than your balance is the number one lesson in FICO physics. If you pay your balance on the due date, the high balance has already been reported to the bureaus. I pay mine three days *before* the statement closes. It’s a game-changer.
The Low-Tech Tools That Actually Saved My Score
While everyone else is looking for the next AI-powered app, I’m over here advocating for a physical folder and a highlighter. In my experience, the danger of using credit repair software without a plan is that it makes you passive. You need to be active. I keep a physical ‘Credit Bible’—a three-ring binder where every dispute letter and every piece of the documentation that proves a payment was made on time is filed by date. This isn’t just for organization; it’s for legal protection. If a bureau refuses to fix a mistake, having a physical trail makes it much easier to force a manual review when the bureau robots say no. I once won a dispute simply because I could provide the exact certified mail receipt number from eighteen months prior, proving the bureau had ignored my previous evidence.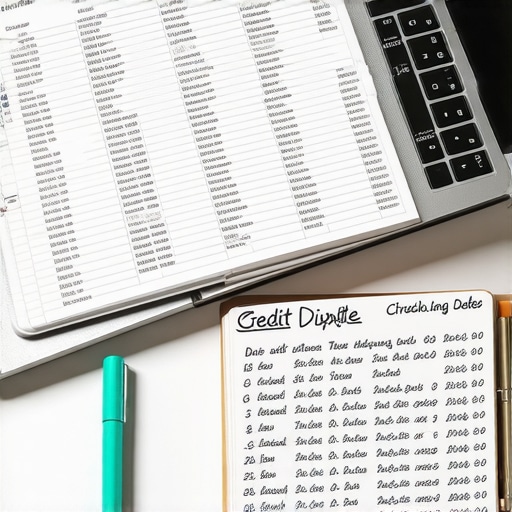
How do I keep my credit score growing every month?
Maintenance isn’t just about stopping errors; it’s about optimization. I follow the ‘AZEO’ method (All Zero Except One). This means I keep most of my cards at a $0 balance when the statement cuts, leaving only one card with a small, 1% balance. According to a technical whitepaper by FICO on the Resilience Index, lenders are increasingly looking at how ‘resilient’ a consumer is to economic shocks. By keeping my reported utilization ultra-low, I’m telling their algorithms that I don’t need credit to survive. This is one of the proven strategies to improve your credit dispute score because it creates a buffer. If an error does pop up, your score is already so high that the hit won’t be fatal. To stay on top of this, you must be monitoring your credit for small changes every single week. I set a calendar alert for every Saturday morning. Ten minutes of review can save you ten months of repair.
What the Future of FICO Looks Like for You
We’re entering an era where ‘Trended Data’ is king. Lenders aren’t just looking at your score today; they’re looking at the trajectory of your balances over the last 24 months. If you’re slowly creeping up in debt, even if you’re paying on time, your score might stall. I predict that within the next three years, effective dispute error resolution to boost your credit score in 2025 will require us to look at utility and rental data more than ever before. To prepare, you should start using tools that report your on-time rent and utility payments now. It adds ‘thickness’ to your file. If you’re ready to take this seriously, I challenge you to do a ‘Line-by-Line Audit’ of your report tonight. Don’t look at the score—look at the dates. Use my specific log you need to keep when calling bureaus to note anything that doesn’t match your personal records. Start that paper trail today, and you’ll thank yourself when you’re ready for that next big mortgage or car loan.
What I Realized While Staring at My Hospital Discharge Papers
The biggest epiphany didn’t come when I was analyzing spreadsheets; it came when I realized that the credit system is entirely mechanical. It doesn’t know you were sick, and it doesn’t care. Accepting this lack of ‘fairness’ is actually liberating because it means you can stop being emotional and start being strategic. One lightbulb moment for me was realizing that why paying off a collection does not always raise your score is the most important rule to memorize. It shifted my focus from ‘paying people back’ to ‘protecting my data.’ I also learned that mastering credit repair is more about the frequency of your follow-ups than the complexity of your vocabulary. Bureaucracy moves for the person who doesn’t go away.
The Toolkit That Kept Me Sane When the Collectors Called
I didn’t do this alone; I had a few ‘North Stars’ that I turned to every time I felt overwhelmed. First, the Consumer Financial Protection Bureau (CFPB). They are the only ones the big bureaus actually fear. If you’ve been doing effective dispute error resolution for months with no luck, filing a CFPB complaint is like bringing a lawyer to a fistfight. Second, I swear by the Fair Debt Collection Practices Act (FDCPA) handbook. Knowing your rights—like the fact that they can’t call you at work if you tell them not to—takes the power back. Finally, I never made a move without the specific log you need to keep when calling bureaus. That binder was my shield and my sword.
#IMAGE_PLACEHOLDER_E#
Your Credit Score Is Not Your Worth
At the end of the day, a three-digit number shouldn’t dictate your happiness. I spent months feeling like a failure because my FICO was in the gutter, but I was the same person with the same integrity. Rebuilding is a marathon, not a sprint. Whether you are trying to build credit fast or just trying to figure out how to handle a medical bill that went to collections unfairly, give yourself some grace. You’ve survived the hospital; you can survive a credit dispute. You are now armed with the tactics, the mindset, and the tools to take back control of your financial future. Have you ever had a medical bill surprise you after a long recovery, or felt like the system was rigged against you? Let me know in the comments below; I’d love to hear your story.