
I stood in that leasing office, holding a cashier’s check and a lot of hope, only to watch the manager’s face turn into a mask of pity. My credit score, which I thought was ‘okay-ish,’ had plummeted sixty points in two months. Why? Because my ex had missed three payments on a joint retail card I forgot existed. I realized then that the law might say we’re done, but the credit bureaus still see us as a team—and it’s a team I no longer wanted to play for. It was a visceral, sickening moment of realization that my financial freedom was still tied to someone I was trying to leave behind. This isn’t just about numbers; it’s about the ability to move on with your life without looking over your shoulder.
Taking Back the Reins Without the Legal Drama
Breaking up is hard, but untangling your FICO score from a former partner can feel like navigating a minefield. You don’t have to get back into a shouting match or hire an expensive mediator just to clean up your report. I’m going to show you how to identify the ghosts in your credit file and exorcise them solo. We are going to look at understanding FICO dispute errors and credit repair hacks that actually move the needle. I learned the hard way that a divorce decree is just a piece of paper to a bank; they care about who signed the original contract, not who the judge said *should* pay. If your name is on the dotted line, the debt is yours in the eyes of the bureaus.
Is it actually possible to fix this without sending a single text to your ex?
You might be worried that you need their permission or a signature to remove yourself from accounts, but that’s a common misconception. I made the massive mistake of waiting for my ex to ‘do the right thing’ and close our shared accounts. Spoiler: they didn’t, and I ended up with a collection notice for a gym membership I hadn’t used in years. Instead, I should have realized that why an individual account is safer than a joint account for your credit is a lesson you need to learn before the late payments start rolling in. According to a study by Experian, divorce doesn’t directly show up on your credit report, but the fallout from missed payments on joint debt is the real killer for your FICO. Have you ever checked your report only to find an account you thought was long gone still lurking there? It’s a total buzzkill. Today, we’re stopping that cycle by using the 30-day rule for disputing new errors and protecting your future from someone else’s spending habits. If you’re worried about your score suddenly dropping during this messy transition, keep an eye on why your credit card company might lower your limit without warning. Let’s get to work on making your credit report as single and successful as you are.The law doesn’t care about your feelings, and neither does the credit bureau’s automated algorithm. To clear the wreckage of a shared financial past, you need a surgical approach. Think of your credit report like a garden; right now, it’s overgrown with weeds planted by someone else. You can’t just wish them away; you have to pull them out by the root.
Scan Your History for Hidden Joint Liabilities
Before you can fix the damage, you have to find where the bodies are buried. Most people glance at their score and panic, but you need to dive into the line items. Look for accounts marked as ‘Joint’ or ‘Authorized User.’ Even if you haven’t touched that department store card in five years, if your ex misses a payment, your score takes the hit. I remember the sinking feeling of finding a $400 collection for a ‘shared’ utility bill from an apartment I’d left three years prior. I realized then that the simple way to proofread your credit report for identity errors is the first line of defense in reclaiming your name. 
Cut the Authorized User Anchor Immediately
Being an authorized user is like being a passenger in a car; you get the benefit of the ride, but you have no control over the steering wheel. If your ex is driving that car into a ditch, you need to jump out. This is the easiest fix in the book because you don’t need their permission. You can call the creditor yourself and ask to be removed. I’ve seen scores jump thirty points in a single billing cycle just by shedding a high-balance account where the person was only an authorized user. You have to understand why your authorized user status might be lowering your fico score before you can decide which ties to cut and which to keep.
Write the Letters That Actually Get Results
When you find errors—and you will—don’t use the ‘dispute’ button on a credit monitoring app. That’s a trap. It often forces you to waive your right to a full investigation. Instead, you need to go old school with certified mail. The goal is to bypass the computer and get a pair of human eyes on your file. I spent months shouting into the void with online forms until I learned that the specific phrase that triggers a human review of your dispute is what actually forces a bureau to do their job. Stop wasting time and stop sending generic dispute letters if you want real results. When I finally sent a custom letter with a copy of my old lease and a utility shut-off notice, the ‘shared’ debt that haunted me was gone in twenty days.
Build Your New Score on Solid Ground
Once the ghosts are exorcised, you have to fill that vacuum with positive data. You are essentially starting over, and that requires a new, solo foundation. If your credit is too bruised to get a standard card, don’t sweat it. I used a small deposit to open a secured line of credit. It felt like training wheels at first, but it worked. Learning how to use a secured card to jumpstart a 700 score is the fastest way to prove to lenders that you are a reliable entity on your own. It’s about creating a paper trail of responsibility that has absolutely nothing to do with your past relationship. I used the paper trail method for deleting wrongful medical bills logic to clean up old residency disputes, and suddenly, the person the banks saw was the person I actually was: independent and capable.Most people believe that settling an old debt is the most responsible thing they can do for their financial health. However, in the world of credit scoring, good intentions can backfire. Understanding why paying off a collection could actually drop your score is one of the most painful lessons in credit repair. If you pay an account that hasn’t been reported in several years, the bureaus update the ‘date of last activity.’ To the FICO algorithm, a ‘dead’ negative item suddenly looks like a brand-new failure. According to data from FICO, the standard FICO Score 8 model does not differentiate between a paid and an unpaid collection; the negative weight remains the same regardless of the balance.
Paying Off Old Debts is Often a Scoring Trap
When you are trying to move on, your instinct is to clean the slate. But if that debt is five or six years old, it is close to falling off naturally. By making a payment, you might inadvertently ‘re-age’ the item in the eyes of certain lenders, making the delinquency appear fresh. Instead of blindly paying, you need to master mastering credit repair dispute errors and fico optimization to ensure you aren’t resetting the clock on your own recovery. 
Keep Your Rights by Avoiding the Online Dispute Button
The ‘Oops’ factor often happens when people use the convenient dispute button inside their banking apps. It’s a trap. When you click that button, you are often agreeing to an automated process that limits your ability to appeal or provide physical evidence. I’ve seen countless people lose their right to a fair investigation because they wanted a shortcut. This is why you should never use the dispute button on a banking app. A 2021 report from the Consumer Financial Protection Bureau (CFPB) highlighted that these automated systems frequently overlook the nuanced documentation consumers provide, leading to valid disputes being dismissed as ‘frivolous.’
Does Making a Partial Payment Reset the Legal Clock?
This is a sophisticated concern for anyone dealing with ‘zombie debt.’ In many states, making even a five-dollar payment on an expired debt can restart the statute of limitations, allowing a collector to sue you for a balance that was previously unenforceable. This is why you must learn how to identify a zombie debt on your credit report before you engage with any collector. Always demand validation first. Using the phrasing you need in a debt validation letter forces the collector to prove they actually have the right to collect before you put your score—or your bank account—at risk. Once you’ve cleared the path, you can focus on positive habits like the 15-15 rule for payments to keep your momentum going. Have you ever fallen into the ‘paid collection’ trap only to see your score plummet? Let me know in the comments.I’ve realized that cleaning up your financial past is only half the battle. The real challenge is keeping that slate clean while the bureaus are constantly updating their algorithms behind the scenes. If you aren’t careful, the same errors you fought so hard to remove can crawl back onto your report like a persistent weed. This is where most people fail—they fix the problem once and then stop looking at their file. To win long-term, you need to transition from a repair mindset to a maintenance mindset. I don’t trust the free monitoring apps to give me the full story because they often provide a watered-down version of your actual data. Instead, I use a dedicated spreadsheet to track my ‘date of last activity’ for every negative item. This ensures I know exactly when something should fall off, preventing the bureaus from conveniently forgetting to delete it.
Build an Evidence Log to Protect Your Wins
Stop relying on your memory or random digital screenshots saved in buried folders. I started keeping a physical ‘Credit Bible’—a chronological binder where every letter sent and every response received is filed. This is the evidence log that wins every investigation because it demonstrates a pattern of non-compliance by the bureaus that a judge or a supervisor can’t ignore. When you possess the documentation that forces a bureau to manually verify your data, you stop being a victim of their automated ‘e-OSCAR’ systems. The Consumer Data Industry Association (CDIA) sets the technical Metro 2 Format standards for how data must be reported, and if a creditor cannot match that hyper-specific technical standard against your physical proof, the item is legally required to be deleted. 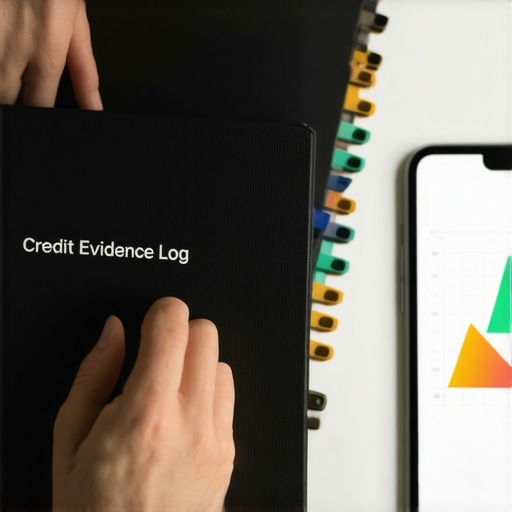
How do I keep my FICO score climbing year after year?
Maintenance is about being proactive rather than reactive. I check my full reports every quarter—not just the score, but the raw data. You need to follow the ultimate guide to dispute errors and credit building in 2025 to stay ahead of how banks are now reporting ‘trended data.’ Instead of just looking at your balance today, lenders now see your behavior over the last two years. If you are trying to scale your score into the high 700s or 800s, you must learn how to bypass the ai review in credit disputes. The robots are getting smarter at scanning for templates, so your documentation has to become more detailed and human-centric.
Trended Data is the Future of Lending
Looking ahead, the credit landscape is moving away from static snapshots. We are seeing a massive shift toward sophisticated models like FICO 10T, which rewards long-term stability and consistent payment patterns rather than quick, temporary fixes. Understanding the difference between fico 8 and fico 10t for new borrowers will be the deciding factor in whether you qualify for the lowest mortgage rates in the coming years. Using the hidden document that wins almost every credit dispute—which is usually a letter of inaccuracy from the original creditor’s own billing department—is the ultimate tool for your arsenal. I also recommend sending the documentation bureau reps hate to receive, such as original signed contracts that prove a debt was miscalculated. Go grab a physical folder today and print out your most recent reports. Start your log now before another error sneaks in and ruins your progress.
The Hard Truths About Reclaiming Your Financial Name
Reflecting on my journey from a shared financial nightmare to independent stability, I realized a few things that the standard advice columns never mention. First, your credit report is a legal document, not just a score. Every line is an opportunity for a correction. Second, silence is often interpreted as agreement by the bureaus; if you don’t speak up, the error stays. Third, never assume a creditor will do what they promised over the phone without written confirmation. I highly recommend reading up on fico insights how dispute errors affect your score and what to do to see how even small mistakes can have a massive ripple effect on your interest rates.
My Essential Recovery Toolkit
You don’t need expensive software to win this battle. Here is what I actually used to climb back to a 750: 1) A simple accordion folder to store every single piece of mail from debt collectors. 2) The official government-mandated site for free weekly reports, because credit monitoring apps often lag by weeks. 3) The strategies found in mastering fico proven strategies to improve your credit dispute score which helped me prioritize which accounts to attack first. Finally, I relied heavily on the credit repair blueprint fixing errors and strengthening your financial profile to ensure I wasn’t just deleting negatives but also building new, positive history.
Your Future Starts With the Next Dispute Letter
Rebuilding your life after a separation is exhausting, but taking control of your financial data is one of the most empowering things you can do. You aren’t just fixing a number; you are reclaiming your autonomy. The process of credit building and credit repair takes time, but every single dispute error you resolve brings you one step closer to the keys of your own home or a car loan on your own terms. Your FICO score belongs to you, and no one else. Have you ever found a mistake on your report that felt like a ‘ghost’ from your past? Let me know in the comments below.