
I stood at the grocery store checkout, sweat beads forming on my forehead, praying my card wouldn’t decline—not because I didn’t have the money, but because I knew my credit limits were pushed to the absolute brink. I had three different cards, and every single one was sitting at about 92% utilization. Even though I’d never missed a payment, my FICO score looked like it had been through a paper shredder. I felt like I was failing a test I hadn’t even studied for. It was that moment of sheer embarrassment that forced me to realize that simply “having credit” isn’t the same as managing it effectively. If you’ve ever felt that pit in your stomach when checking your banking app, I’m here to tell you that there’s a way out of the high-utilization trap that doesn’t involve winning the lottery. We are going to fix that “maxed-out” appearance and get your score breathing again.
Stop Draining Your Savings to Fix One Card
When I first started trying to fix my score, I made a massive rookie mistake: I threw every spare cent I had at my smallest card to get it to a zero balance, while my largest card stayed pegged at 98%. I thought the “win” of a zero balance would skyrocket my score. Instead, it barely budged. I eventually learned that why your credit utilization ratio is more important than your balance than almost any other factor in the “Amounts Owed” category. Lenders don’t just look at the total debt; they look at how close you are to the limit on every individual account. By spreading your payments across all cards to bring them all below certain thresholds (like 50% or 30%), you signal to the FICO algorithm that you aren’t in a desperate cash crunch. [image_placeholder]
Is micro-managing your balances actually worth the headache?
You might be thinking, “Does the bank really care if I have $500 on three cards or $1,500 on one?” The answer, frustratingly, is yes. According to data from the Consumer Financial Protection Bureau (CFPB), credit utilization is one of the most influential factors in credit scoring models, often carrying nearly as much weight as your payment history itself. In fact, the impact of a high limit card on your credit utilization can be the difference between a mortgage approval and a rejection letter. By the time we’re done today, you’ll know exactly how to shuffle these numbers to your advantage. Have you ever tried to pay down a card only to see your score drop anyway? I’d love to hear your story—hit me up on our contact page.
The Magic of the Mid-Cycle Payment
One thing no one tells you is that your score is a snapshot. If you wait until the due date to pay, the high balance has already been reported to the bureaus. This is why why you should pay twice a month for maximum fico points is the best “neighborly advice” I can give. It’s a simple trick that changed everything for me. I also realized that why a zero balance is not always the best for your score because it can sometimes make your account look inactive. We’re aiming for that “Goldilocks” zone—not too high, not too low. In the next section, we’ll dive into the specific math of the “Spread Strategy.”To execute the spread strategy effectively, you first need to see exactly what the bureaus see. I remember sitting at my kitchen table with three different screens open, trying to cross-reference my bank apps with a free credit site. It was a disaster. I realized then that why you should always request a paper credit report is essential because the digital versions often truncate the very details you need to win. Once I had that physical paper in my hand, I spotted the ghost: an old medical bill I thought was long gone. I had to quickly learn how to handle a medical bill that went to collections unfairly before I could even touch my utilization. If your foundation is cracked with errors, no amount of debt-shuffling will fix the house.
Audit Every Line for Hidden Reporting Errors
Before you move a single dollar, you must ensure the data is accurate. Lenders and bureaus make mistakes more often than you’d think. I once found an account listed as ‘open’ that I’d closed three years prior, and the balance was stuck at $400. That $400 was eating into my utilization every single month. You need to how to audit your credit report for incorrect account dates and statuses. If you find a mistake, don’t just call them. Phone calls leave no paper trail. You need to pursue effective dispute error resolution to boost your credit score in 2025 by documenting everything in writing.
Why Certified Mail is Your Secret Weapon
When I first sent a dispute, I used a regular stamp. Big mistake. It ‘disappeared’ according to the bureau. That’s why you should always send dispute letters via certified mail with a return receipt. It’s like having a physical signature that says, ‘I know you got this, and the clock is ticking.’ This forces them to take your file seriously rather than tossing it into the automated ‘frivolous’ pile.
Balance Your Buckets to Trick the Algorithm
Think of your credit cards like a row of water buckets. If one bucket is overflowing (maxed out) and the others are empty, the FICO algorithm sees a flood risk. If you take that same amount of water and spread it evenly so every bucket is only 20% full, the ‘risk’ disappears in the eyes of the computer. 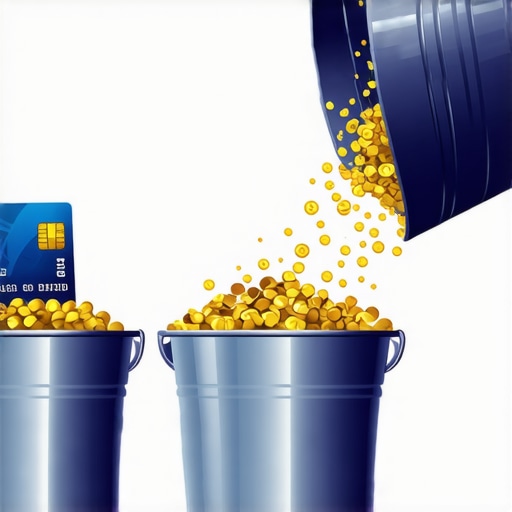 I applied this by taking a $1,000 tax refund and instead of paying off my smallest $1,000 card, I put $333 on three different cards. My score jumped 45 points in one cycle because I dropped three cards below the 30% threshold simultaneously.
Focus on Your Oldest Anchor Accounts
While you are spreading your payments, don’t forget your foundation. It is often easier to how to get a higher credit limit on your oldest card than to get a new one. A higher limit on an existing card instantly dilutes your utilization ratio without the ‘hard hit’ of a new application. Finally, don’t forget the small balance hack that adds 20 points to your fico 2—leaving a tiny balance of $5 to $10 on one card shows you are using credit responsibly without being ‘over-extended.’But here is where the ‘common knowledge’ usually stops, and where most people accidentally sabotage their progress. Most ‘experts’ will tell you that paying off an old debt is always a win for your score. I’m here to tell you that’s a dangerous half-truth. In my experience, if you aren’t careful, writing a check to a debt collector can actually cause your score to drop further.
Why Writing a Check to a Debt Collector Can Backfire
The nuance lies in ‘Date of Last Activity.’ When you pay an old, dormant collection, you might inadvertently ‘re-age’ the debt in the eyes of the scoring algorithm. While the balance goes to zero, the account status updates to ‘recently active,’ which can sometimes pull your score down because the penalty of the collection is suddenly fresh again. This is specifically why paying off a collection does not always raise your score immediately. Before you send a dime, you should consider a ‘pay-for-delete’ agreement or at least understand fico insights how dispute errors affect your score and what to do when an update doesn’t go your way. FICO research indicates that while newer scoring models like FICO 9 treat paid collections more leniently, the older models still used by most mortgage lenders—FICO 2, 4, and 5—do not differentiate between a paid and an unpaid collection in the same way. 
Why do the three major bureaus never seem to agree on your number?
If you’ve ever looked at your Experian report and then jumped over to TransUnion only to see a 40-point difference, you aren’t alone. This happens because not every creditor reports to all three bureaus; some only report to one or two to save on fees. This is fundamentally why your score is different on experian and transunion. If you are preparing for a big purchase, you must how to find out which credit model your lender uses so you aren’t blindsided by a lower middle score. Have you ever fallen into this trap of focusing on the wrong bureau? Let me know in the comments.
Don’t let robotic dispute templates flag your file as frivolous
One of the biggest ‘oops’ factors I see today is the over-reliance on automated credit repair apps. Everyone wants a quick fix, but the credit bureaus have sophisticated AI designed specifically to catch and reject ‘form letters’ generated by software. When a bureau identifies a mass-produced dispute, they often tag it as ‘frivolous,’ which can stop your repair process dead in its tracks for 30 days or more. I’ve seen the problem with using credit repair software for complex errors firsthand—it lacks the human touch needed to explain why a specific date or balance is wrong. If you get hit with a rejection, you’ll need to know how to fight a frivolous dispute response from the bureau by providing manual, physical evidence that a machine simply can’t replicate. It is always better to follow the ultimate guide to dispute errors and credit building in 2025 and craft a custom narrative. Real credit repair is a marathon of accuracy, not a sprint of automation.Once you’ve cleared the debris from your report, the real work begins—the maintenance phase. I used to think I could just ‘set it and forget it’ once I hit a 740, but I learned the hard way that life has a habit of throwing curveballs. To stay on top of it, I’ve developed a system that goes beyond just checking an app once a week. I started using a dedicated physical binder—my ‘Credit War Room’—to document every interaction because you need to know how to monitor your credit for small changes that matter. A single misreported late payment can wipe out months of hard work if you aren’t vigilant.
Keep a paper trail that robots can’t ignore
The biggest tool in my arsenal isn’t an app; it’s a simple spreadsheet I call the specific log you need to keep when calling bureaus. In this log, I record the date, the time, the representative’s name, and their ID number for every single call. Why? Because under Section 611 of the Fair Credit Reporting Act (FCRA), credit bureaus are required to conduct a ‘reasonable reinvestigation’ of disputed information. If they fail to do so, your log becomes your primary evidence for a potential legal escalation. I also keep a physical copy of every ‘Results of Investigation’ letter I receive to avoid being caught off guard by bureaucratic resets. #IMAGE_PLACE_HOLDER_D#
How do I keep my score from dropping again?
Long-term stability comes from diversification. If you only have one type of credit, your score will always be fragile. I started looking into credit building strategies correcting dispute errors for better fico in 2025 to ensure I had a healthy mix of installment loans and revolving lines. This isn’t about spending more money; it’s about showing the algorithm you can handle different types of financial responsibility. One specific move I recommend is to how to get a higher credit limit on your oldest card every six months. This naturally lowers your utilization and builds a massive buffer against small balance fluctuations. I’ve found that credit repair tips correcting dispute errors effectively only work if you have a solid foundation of open, active accounts to support the growth.
The shift toward automated AI verification
Looking ahead, the game is changing. According to a 2023 CFPB report on the e-OSCAR system, bureaus are increasingly relying on automated ‘matching’ logic that can sometimes miss the nuance of your specific situation. This is why following the ultimate guide to dispute errors and credit building in 2025 is so critical—you have to provide the kind of specific, physical proof that forces a human to step in. If you’re just starting this part of the journey, I want you to go to your bank app right now and request a limit increase on your oldest account. It’s a five-minute task that can set the stage for your next 50-point jump. If you’re unsure how to phrase it, check out our guide on dispute errors on your credit report a step by step guide for 2025 for the right vocabulary and professional approach.
The Lessons That Finally Moved the Needle
If I could go back and talk to my younger self—the one sweating at the grocery checkout counter—I’d tell him that credit isn’t a grade of his character; it’s just a math problem. Here are a few lightbulb moments I had while mastering credit repair dispute errors and fico optimization in my own life. First, I realized that the credit bureaus aren’t your friends or government agencies; they are data brokers. Once I stopped expecting them to be “fair” and started treating every dispute like a legal case, my success rate skyrocketed. I also learned that small numbers carry massive weight. I used to ignore tiny $15 balances, but those little anchors on multiple cards were dragging down my score more than one large balance. Finally, I discovered that timing is everything. Knowing exactly when your bank reports to the bureaus is like having the cheat codes to a video game; you can make your debt disappear right before the snapshot is taken.
The Gear I Use to Fight the Bureaus
You don’t need expensive, subscription-based software to fix your life, but you do need a system that keeps you organized. My personal “war room” consists of three non-negotiable tools that I trust more than any automated app. First, a physical binder for my Certified Mail receipts—if it isn’t tracked with a signature, the bureau can claim it never arrived. Second, I always keep a copy of the one document that forces a bureau manual review 2 on hand for when the automated e-OSCAR system keeps spitting back rejections. Finally, I rely on a dedicated spreadsheet to track every point of contact. Implementing mastering fico proven strategies to improve your credit dispute score requires a level of detail-oriented record-keeping that digital dashboards often gloss over. These tools give me the paper trail needed to hold creditors accountable under the law.
Take Back Control of Your Financial Narrative
Your financial future isn’t written in stone. It’s written in a digital file that you have the absolute legal right to challenge, correct, and improve. Whether you are currently buried under a stack of medical bills or just trying to shake off the “maxed-out” look of high utilization, the steps remain the same: audit the data, dispute the errors, and optimize the timing. The process of credit building is a journey of a thousand small payments and a few well-placed, certified letters. Don’t wait for a “better time” to start or for the bureaus to fix themselves. Every month you spend in the high-utilization trap is a month of higher interest rates and missed opportunities. Have you ever struggled with a maxed-out card despite making all your payments on time? Let me know in the comments below!